

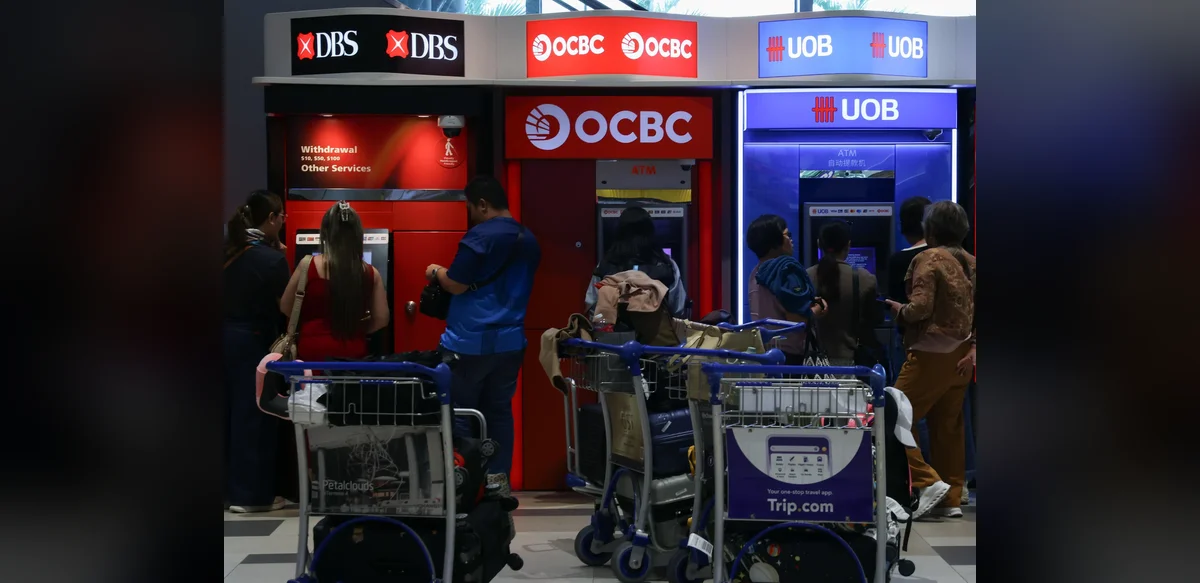
Singapore’s banking sector has drawn renewed investor attention following the release of first-half financial results from major institutions. Shares of DBS and OCBC climbed noticeably as the market digested the figures, reflecting confidence in their operational performance. At the same time, analysts have pointed out that dividend yields, while lower than in previous periods due to share price gains, continue to offer appealing returns for income-focused investors.
The compression in yields stems directly from the upward movement in stock prices after the earnings announcements. Despite this adjustment, the payouts remain competitive when compared with other sectors and regional peers. This balance between capital appreciation and steady income has kept the stocks attractive to a broad range of shareholders, including institutional funds and retail participants.
UOB, often viewed as the smaller player among the three local banks, has not seen the same immediate price momentum. However, market observers suggest its underlying fundamentals and growth trajectory could present opportunities that are currently underappreciated. The bank’s conservative approach to lending and its diversified regional exposure may provide resilience in varying economic conditions.
Investors evaluating the sector are weighing the trade-offs between established leaders and the potential for catch-up gains. Dividend sustainability remains a key consideration, especially as interest rate environments evolve. The current yield levels, though moderated, still support the case for holding these equities over the medium term.
Broader market sentiment toward Singapore banks has been influenced by domestic economic indicators and regional trade flows. Stronger-than-expected results from DBS and OCBC have reinforced the view that the sector is well-positioned to navigate challenges. UOB’s quieter performance leaves room for further analysis on whether its valuation offers relative value.
Portfolio managers continue to monitor payout ratios and capital adequacy metrics closely. The combination of solid earnings and reliable dividends has historically made the trio a staple in many local investment strategies. Recent price movements have simply recalibrated expectations without diminishing the overall appeal of the income component.
Looking ahead, attention will likely shift to upcoming policy decisions and their impact on net interest margins. While yields have tightened, the underlying business models of these banks appear robust enough to sustain distributions. This dynamic keeps the sector relevant for both growth and income objectives within diversified holdings.
In summary, the recent surge in DBS and OCBC shares highlights strong interim results, yet the enduring attractiveness of dividend yields across the group, including UOB’s latent potential, maintains interest among market participants seeking balanced returns.


