

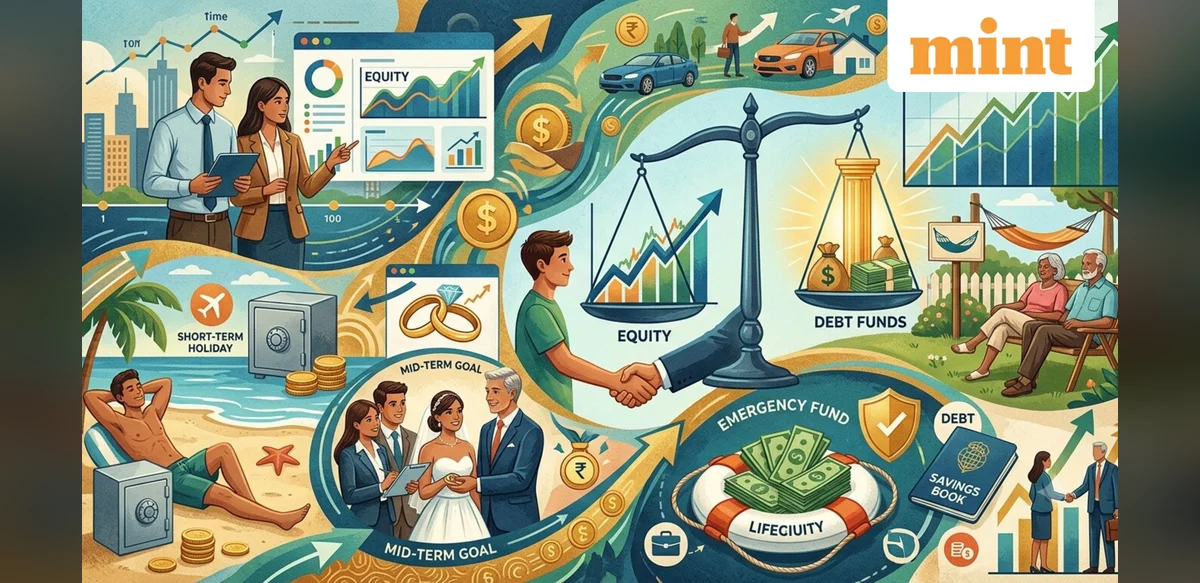
Financial advisors often note that individuals in their twenties and thirties possess a longer time horizon for growth, which frequently leads to recommendations favoring equity investments. However, this does not mean debt mutual funds should be dismissed outright from such portfolios. These instruments continue to serve specific purposes that align with varying objectives and time frames.
Debt mutual funds invest primarily in fixed-income securities such as government bonds, corporate debt, and money market instruments. Their returns tend to be more predictable than those from equities, offering a buffer against market swings. For younger investors building wealth over decades, this stability can help maintain overall portfolio balance, especially when unexpected expenses arise or when reallocating assets becomes necessary.
Liquidity represents another key advantage. Many debt funds allow redemptions within a short period, sometimes as quickly as one business day, without significant penalties. This feature proves useful for goals that may materialize sooner than retirement, such as funding education, travel, or a down payment on property. By keeping a portion of assets in these funds, investors avoid the need to sell equity holdings during unfavorable market conditions.
Diversification benefits also factor into expert guidance. Combining debt and equity components reduces the impact of volatility on total returns. A portfolio weighted heavily toward stocks may experience sharp declines during economic downturns, whereas debt allocations can offset some of those losses. The exact mix depends on personal circumstances, including risk tolerance, income stability, and upcoming financial milestones.
Experts emphasize that investment decisions should reflect individual horizons rather than age alone. Someone planning a major purchase within three to five years might allocate more toward shorter-duration debt funds to preserve capital. In contrast, those with no immediate needs could use debt funds as a tactical holding to rebalance periodically or to park surplus cash temporarily.
Risk considerations remain important. While debt funds generally exhibit lower volatility, they are not entirely risk-free. Interest rate changes, credit quality of underlying securities, and liquidity constraints in certain categories can affect performance. Investors are advised to review fund factsheets, understand expense ratios, and match fund types to their specific requirements.
Regulatory frameworks in India encourage transparent disclosures for mutual fund schemes, enabling better-informed choices. Platforms now provide tools to compare historical returns, portfolio holdings, and risk metrics across categories. Younger investors can use these resources to simulate how different allocations might behave under various market scenarios.
Tax treatment of debt fund gains has evolved, with holding periods influencing applicable rates. Short-term gains are taxed at slab rates, while longer holdings may qualify for different treatment. This aspect should be weighed alongside return expectations when constructing a diversified strategy.
Ultimately, the decision to include debt mutual funds rests on aligning them with defined objectives. Rather than avoiding them due to perceived lower growth potential, many professionals recommend evaluating their role in providing cushion, access, and balance. Regular portfolio reviews help ensure the allocation continues to match changing life stages and market environments.
Financial planning at any age benefits from a measured approach that incorporates multiple asset classes. Debt mutual funds, when selected appropriately, contribute to resilience without compromising long-term growth prospects. Consultation with certified advisors can further tailor these elements to individual profiles, ensuring strategies remain adaptable over time.


