
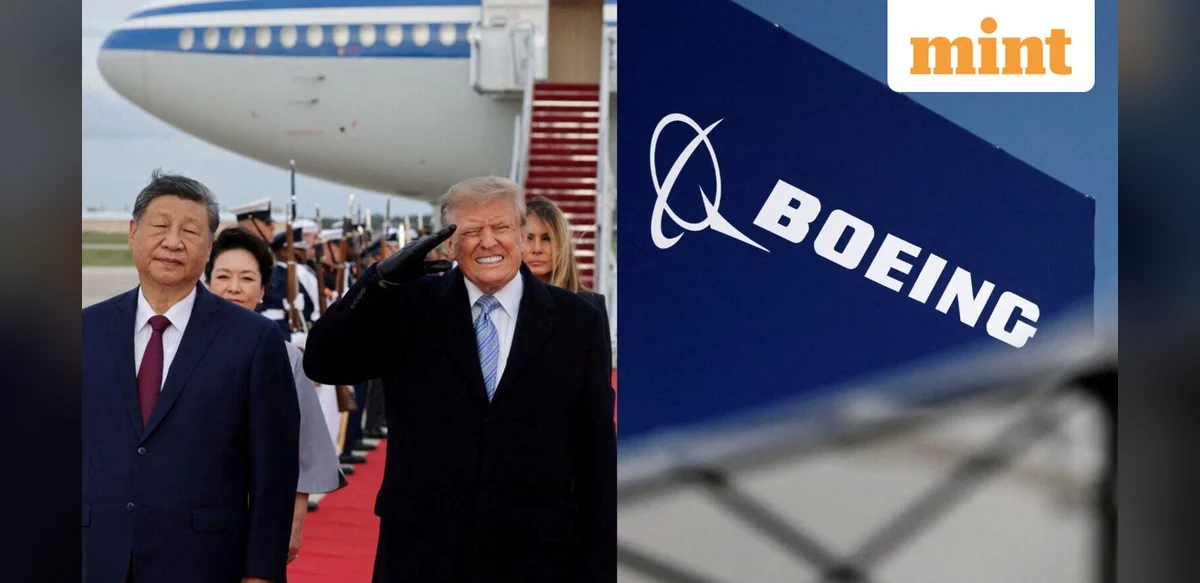
Discussions between high-level representatives from the United States and China took place recently, focusing on ongoing trade matters. Observers noted that commitments for additional purchases of aircraft from a major American manufacturer appeared unlikely during these exchanges.
The American company in question has faced significant barriers in the Chinese market since 2017. In contrast, its primary European competitor managed to increase its presence in the same region over the same period. Restrictions were placed on new shipments and component acquisitions from the US firm as part of broader tariff disagreements between the two countries.
Chinese authorities directed preferences toward the European manufacturer as well as a domestic aircraft producer. This shift occurred against a backdrop of heightened economic tensions. The result has been a noticeable change in market dynamics for commercial aviation in the region.
During the summit talks, participants addressed various aspects of bilateral commerce. However, indications suggested that fresh orders for the affected US aircraft maker would not feature prominently in any immediate agreements. Analysts pointed to the cumulative impact of prior restrictions as a key factor limiting progress on this front.
The European rival benefited from the altered landscape, securing greater access and expanding operations. Meanwhile, the local Chinese manufacturer also received support, contributing to a diversification of suppliers in the aviation sector. These developments have unfolded steadily since the initial imposition of barriers.
Trade negotiations continue to evolve, with both sides exploring avenues for resolution. Yet the aviation industry remains sensitive to the outcomes of these talks. The absence of new commitments for the US company reflects the persistent effects of earlier policy measures.
Industry experts emphasize that resolving such issues may require sustained dialogue beyond the current round of discussions. The focus remains on broader economic relations rather than sector-specific breakthroughs at this stage. Market shares have adjusted accordingly, with the European and domestic options gaining ground.
Overall, the summit highlighted the complexities involved in restoring previous levels of engagement in aircraft procurement. While general trade topics received attention, specific advancements for the restricted manufacturer were not anticipated. This situation underscores the lasting influence of tariff-related decisions on international business operations.
Further updates are expected as talks progress, though immediate changes in delivery patterns or parts supply appear improbable. The competitive environment in commercial aviation continues to reflect these ongoing adjustments in supplier preferences.